
Finance
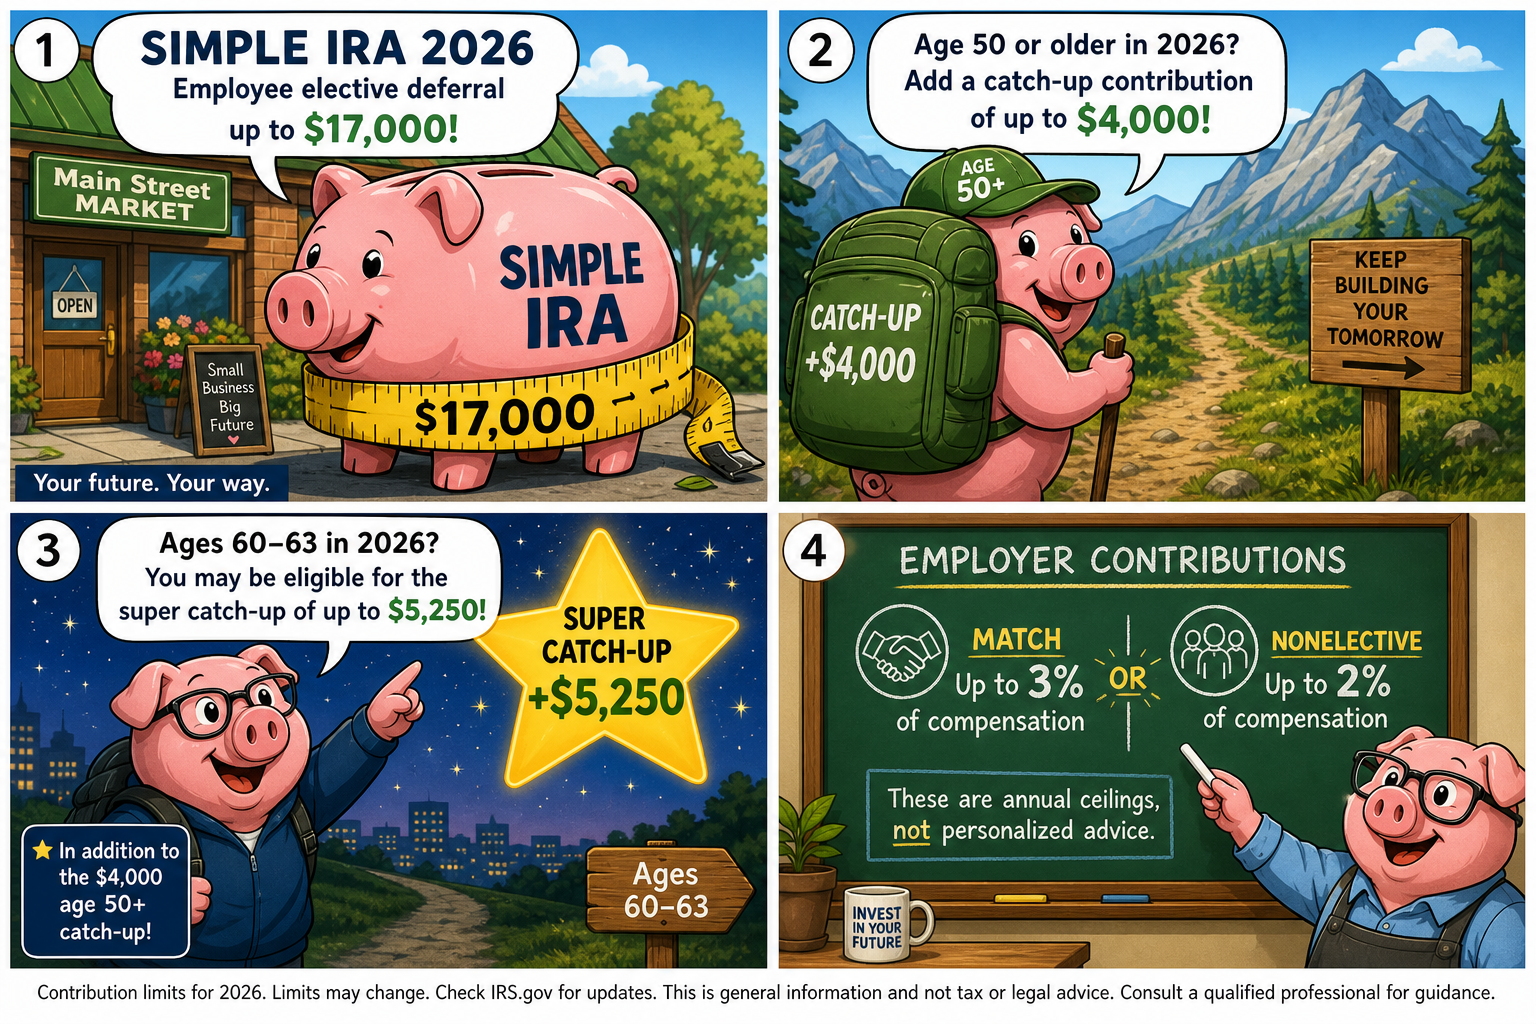
2026 SIMPLE IRA employee limit $17,000; ages 60–63 catch-up $5,250
What happened
The IRS retirement-topics page for SIMPLE IRA contribution limits lists the 2026 employee salary reduction (elective deferral) limit at $17,000. That figure is a published ceiling for eligible participants in a Savings Incentive Match Plan for Employees of Small Employers — not a recommendation to contribute any amount, not a product pitch, and not personalized tax or retirement advice. Educational finance only.
On the same IRS board, the age 50+ catch-up contribution for 2026 is printed at $4,000, and the higher catch-up for ages 60–63 under SECURE 2.0 is printed at $5,250. Compensation taken into account for nonelective contributions is capped at $360,000 for 2026. Those lines sit beside the broader COLA and workplace ceilings already filed in prior packages; today’s board is the SIMPLE IRA salary-reduction / catch-up / higher-catch-up / nonelective-compensation quartet most small-business savers actually see on a plan summary. Ceilings and definitions, not a recommendation. No tickers. No “max this.” The comic is the $17,000 chalk, the piggy-bank sticky, the 50+ / 60–63 card, and a COLA calendar that says educational not advice. Color on the jars and the chalk. White gutters. Ignore any slogan lines that may appear inside artwork; the verified IRS lines are employee salary reduction $17,000, age 50+ catch-up $4,000, ages 60–63 higher catch-up $5,250, and nonelective compensation up to $360,000.
Educational finance here labels published caps so a reader can find them on IRS.gov instead of on a slideshow. Prior days filed 401(k)/403(b) catch-up and elective-deferral lids. Keep politics out. Keep the source URL on the page. Readers get the four SIMPLE numbers, the SECURE 2.0 ages 60–63 line, and the reminder that a contribution-limits page is a ceiling list — not a how-much-should-I-save worksheet.
Why it matters
A SIMPLE IRA dollar limit is a different animal from the 401(k)/403(b) catch-up lines filed earlier. Readers get $17,000 employee salary reduction for 2026, age 50+ catch-up $4,000, ages 60–63 higher catch-up $5,250 under SECURE 2.0, and nonelective compensation up to $360,000 — framed as published contribution ceilings, not advice. Bright teal and gold. White gutters. Stick to the IRS SIMPLE IRA page numbers and skip product pitches.
Conclusion
For 2026, the IRS prints a SIMPLE IRA employee salary reduction limit of $17,000, an age 50+ catch-up of $4,000, a higher catch-up of $5,250 for ages 60–63 under SECURE 2.0, and compensation for nonelective contributions taken into account up to $360,000 — ceilings and definitions for contribution compliance, not personalized tax advice. Source: https://www.irs.gov/retirement-plans/plan-participant-employee/retirement-topics-simple-ira-contribution-limits
Source: IRS