
Finance
2026 key employee threshold rises to $235,000 for top-heavy plan rules
What happened
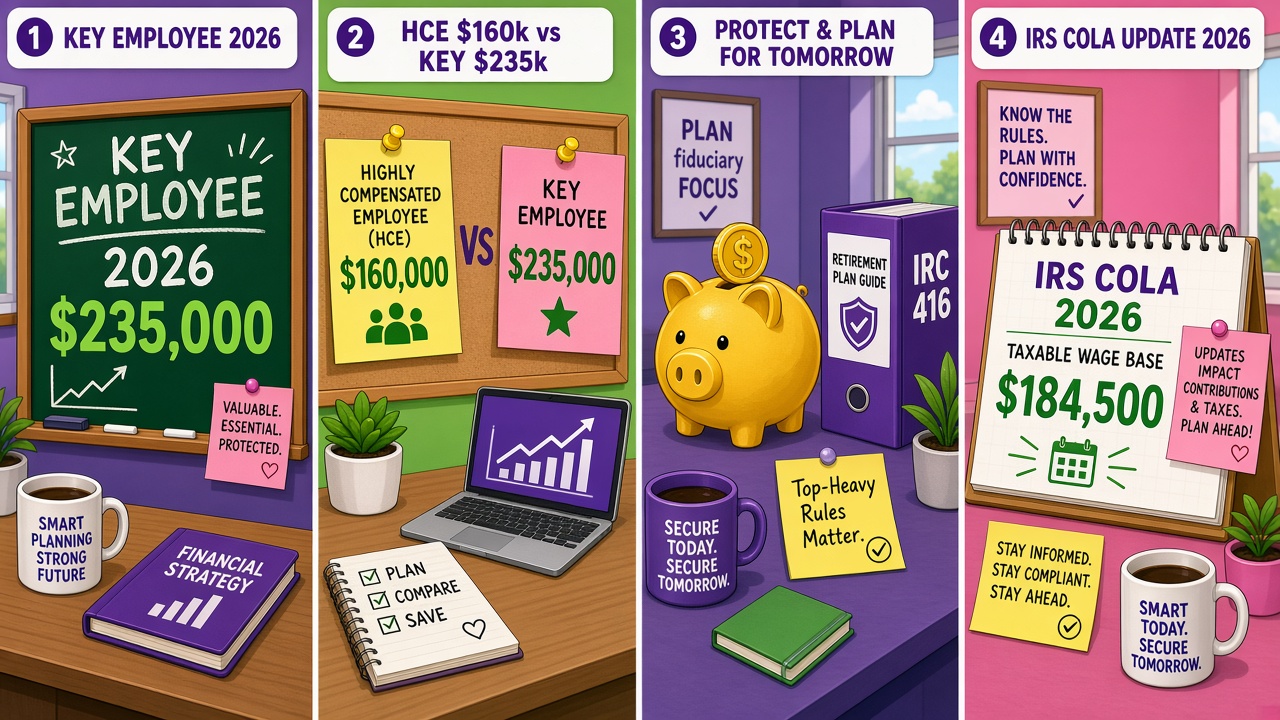
The IRS Cost-of-Living Adjustment (COLA) tables for retirement-plan dollar limitations list the key employee threshold for 2026 as $235,000, up from $230,000 in 2025. That officer/key-employee dollar amount is the published figure used when retirement plans apply top-heavy testing under IRC Section 416(i)(1)(A)(i) — not a salary target, not a recommendation to pay any amount, and not personalized tax or retirement advice. Educational finance only.
On the same COLA page, the highly compensated employee (HCE) threshold stays $160,000 for 2026, and the Social Security taxable wage base rises to $184,500 (was $176,100). Key employee status for top-heavy rules is a different label from the HCE definition used in nondiscrimination testing: a plan that is top-heavy must meet extra minimum-benefit or contribution rules for non-key employees. Ceilings and definitions, not a recommendation. No tickers. No “max this.” The comic is the COLA calendar, the $235,000 key-employee jar, the HCE $160,000 stay chalk, and a sticky that says educational not advice. Color on the jars and the chalk. White gutters. Ignore any wrong prior-year figures that might appear inside artwork; the verified IRS lines are $230,000 (2025) to $235,000 (2026) for key employee, HCE unchanged at $160,000, and wage base $184,500.
Educational finance here labels published caps so a reader can find them on IRS.gov instead of on a slideshow. Prior days filed defined-benefit and other COLA lids. Today’s board is the key employee / officer threshold used for top-heavy plan math under Section 416. Keep politics out. Keep the source URL on the page.
Why it matters
A key employee dollar limit is a different animal from elective-deferral and defined-benefit lines filed earlier. Readers get $235,000 for 2026 (was $230,000 in 2025), HCE still $160,000, taxable wage base $184,500, framed as published plan-testing thresholds — not advice. Bright teal and gold. White gutters. Stick to the IRS COLA page numbers and skip product pitches.
Conclusion
For 2026, the IRS prints a key employee threshold of $235,000 (up from $230,000 in 2025) for top-heavy plan rules under IRC 416(i)(1)(A)(i), with the HCE threshold staying $160,000 and the taxable wage base at $184,500 — ceilings and definitions for plan compliance, not personalized tax advice. Source: https://www.irs.gov/retirement-plans/cola-increases-for-dollar-limitations-on-benefits-and-contributions
Source: IRS