
Finance
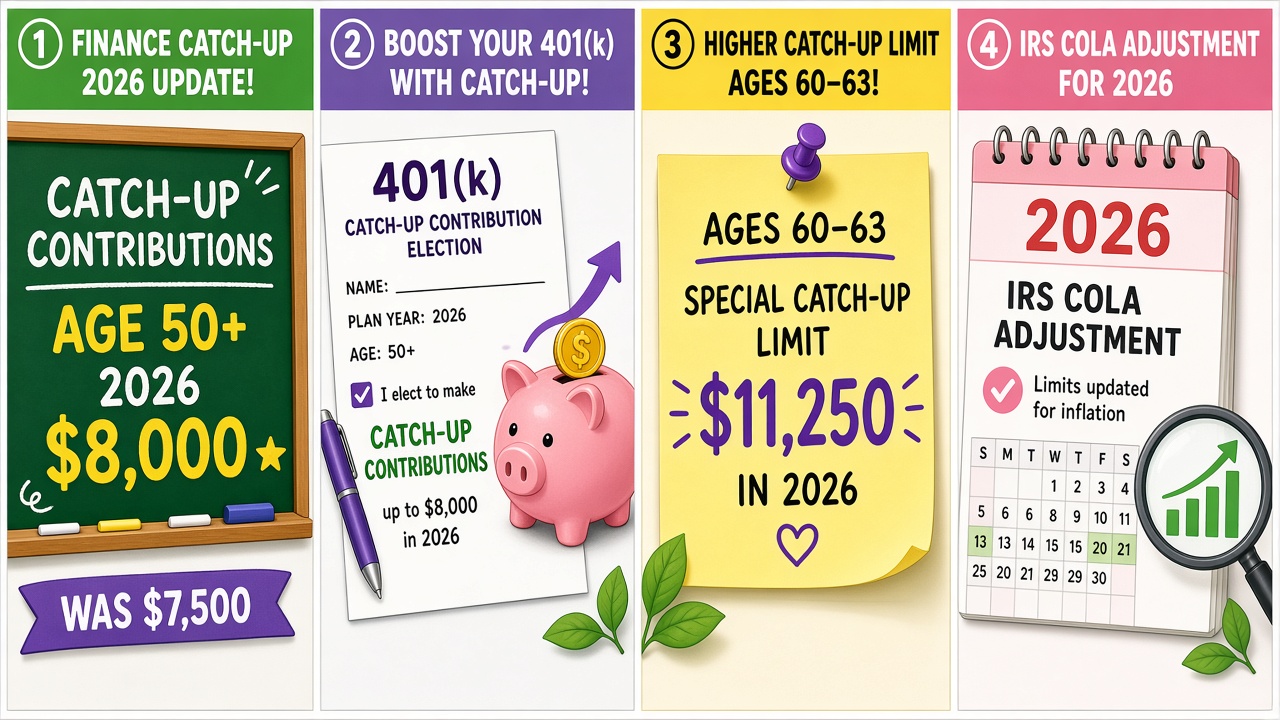
2026 401(k)/403(b) catch-up rises to $8,000; ages 60–63 get $11,250
What happened
The IRS Cost-of-Living Adjustment (COLA) tables for retirement-plan dollar limitations list 401(k)/403(b) catch-up contributions for 2026 at $8,000, up from $7,500 in 2025. That figure is a published catch-up ceiling for eligible participants — not a recommendation to contribute any amount, not a product pitch, and not personalized tax or retirement advice. Educational finance only.
On the same COLA page, the higher catch-up amount for ages 60–63 under SECURE 2.0 is printed at $11,250 for 2026, and elective deferrals for 2026 are listed at $24,500. Those three workplace lines sit beside the broader COLA board already filed in prior packages for IRA lids and other plan ceilings; today’s board is the catch-up / higher catch-up / elective-deferral trio most workplace savers actually see on a plan summary. Ceilings and definitions, not a recommendation. No tickers. No “max this.” The comic is the $8,000 chalk, the 60–63 sticky, the $24,500 jar, and a COLA calendar that says educational not advice. Color on the jars and the chalk. White gutters. Ignore any wrong prior-year figures or slogan lines that may appear inside artwork; the verified IRS lines are catch-up $7,500 (2025) to $8,000 (2026), ages 60–63 higher catch-up $11,250, and elective deferrals $24,500.
Educational finance here labels published caps so a reader can find them on IRS.gov instead of on a slideshow. Prior days filed IRA contribution and IRA catch-up lids. Keep politics out. Keep the source URL on the page. Readers get the three workplace numbers, the year-over-year catch-up delta, the SECURE 2.0 ages 60–63 line, and the reminder that a COLA table is a ceiling list — not a how-much-should-I-save worksheet.
Why it matters
A workplace catch-up dollar limit is a different animal from the IRA contribution lines filed earlier. Readers get $8,000 catch-up for 2026 (was $7,500), ages 60–63 higher catch-up $11,250 under SECURE 2.0, and elective deferrals $24,500 — framed as published contribution ceilings, not advice. Bright teal and gold. White gutters. Stick to the IRS COLA page numbers and skip product pitches.
Conclusion
For 2026, the IRS prints 401(k)/403(b) catch-up contributions of $8,000 (up from $7,500), a higher catch-up of $11,250 for ages 60–63 under SECURE 2.0, and elective deferrals of $24,500 — ceilings and definitions for contribution compliance, not personalized tax advice. Source: https://www.irs.gov/retirement-plans/cola-increases-for-dollar-limitations-on-benefits-and-contributions
Source: IRS